Author: Lasith Siriwardana

  • Thoughts on Risk thanks to Howard Marks

    Thoughts on Risk thanks to Howard Marks

    I recently read Howard Marks’s book The Most Important Thing. For the uninitiated, Marks is a co-founder and co-chairman of Oaktree Capital Management, the world’s largest distressed debt investment firm. He is known for his memos which are posted publicly on the Oaktree website in which he discusses investment insights, investing strategies and the economy. Amongst his list of accolades, potentially the most notable is a very public endorsement by Warren Buffet who has said “when I see memos from Howard Marks in my mail, they’re the first thing I open and read”. He also happens to have a net worth of c. $2.2 billion. It’s therefore unsurprising that Marks’s book is full of investment gems; it is almost certainly the best book on investing I have read.
    Howard Marks, co-founder of Oaktree Capital Management

    Marks’s approach to risk is intuitive and simple, and for me the highlight of his book. It is, however, unorthodox; it differs fundamentally from the notion of risk that many of us (myself included) have been indoctrinated with in undergraduate and graduate finance classes. And the divergence from theoretical financial models is welcome; if understood, Marks’s approach to risk provides actionable investing insight.

    To understand it, we must consider the fundamental relationship in investing: that between risk and return. For an investor to be willing to take on more risk, he must be enticed by more return. Consider the choice between two assets, A and B. A and B both have equal returns but A is riskier than B. We would of course choose to invest in B. This is driven by the fact that we dislike risk; in economic jargon we are risk averse.

    Can you spot the cardinal misnomer I’ve committed in the last paragraph? In place of where I should have said expected returns I’ve instead referred to returns. I misrepresented something which is stochastic as deterministic. More risk doesn’t guarantee higher returns – it just means we can expect higher returns. To quote Marks “there is nothing to say that those higher returns have to materialize”. This is an important idea and can be captured by thinking of the capital market line as in Figure 2 instead of Figure 1.
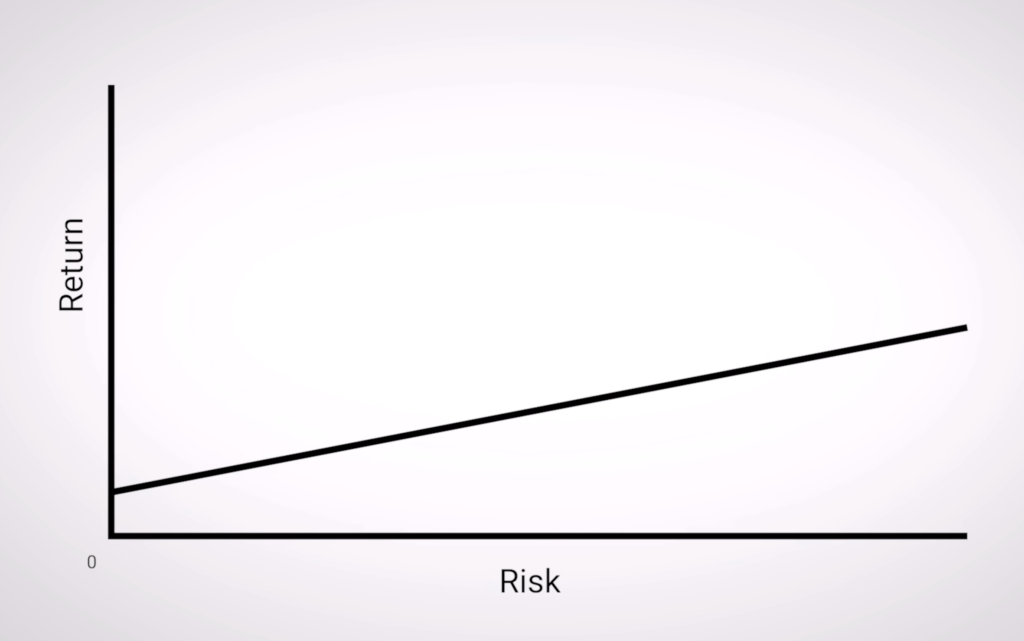
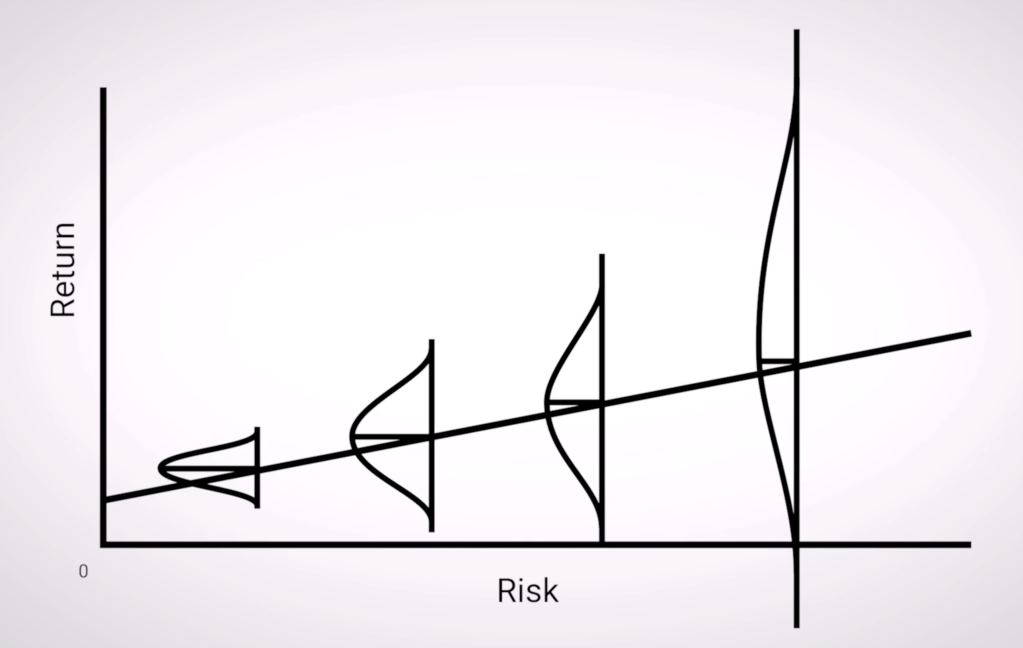
    Figure 1: Looks deterministic
    Figure 2: But it’s actually stochastic

    So far we cannot fault the theory. Finance professors are careful to include expectation symbols before returns in their capital market model derivations. The notion of risk, however, has suffered from simplification to the extent that a layperson’s understanding of risk closely rivals that of a Masters in Finance student entering the asset management industry.

    Risk is measured in the theory as variance of returns, Var(R). Variance simply measures the spread of returns and gives academics an easy number to work with. But spread of returns (a.k.a volatility) isn’t really what people think about when they refer to risk. If it is, it isn’t what they mean deep down. Investors don’t demand higher returns from an asset just because it has a higher spread of returns. A higher spread could be biased to higher returns, it could be biased to lower returns. This can be visualised by adding skewness to the vertical distributions in Figure 2. It is clear that the direction of such bias (which we can measure with second order moment, kurtosis) is what investors really care about.1 They demand higher returns because they risk losing money.2 This is what truly drives the risk-return relationship.

    Now the final point about risk made by Marks, which I believe is somewhat understated in his book, is that the extent to which investors dislike risk (i.e. their degree of risk aversion) is not static. This is contrary to the assumption often made in financial theory. Marks emphasises that risk aversion varies throughout time and in coordination with the boom-bust cycle. The investment cycle, like the business cycle, is characterised by booms and busts. In the boom phase of a cycle, investors may not demand as much expected return to take on X amount of risk. In other words, their risk aversion is low. In contrast, during a bust investors will demand a higher expected returns to take on the same X amount of risk – risk aversion is high. We can visualise this using the capital market line: the higher investors’ risk aversion, the steeper the capital market line will be. The lower the risk aversion, the shallower the capital market line will be.3 This phenomenon, he believes, provides opportunities for the enlightened investor.

    During a bust, varying risk aversion means that rising fear widens risk premiums at the same time that most investors de-risk their portfolios. Marks calls this the “perversity of risk”. The prudent investor would instead add risk to their portfolio when others are de-risking because the premium for doing so is currently high. Again quoting Marks, “when everyone believes something is risky, their unwillingness to buy usually reduces its price to the point where it’s not risky at all”. This, to me, is the one most important piece of investing advice in his book.

    When a friend pointed me towards Marks’s book, I took his recommendation, but with a pinch of salt. I said “I do occasionally think that there is no point reading books by people who have done well in finance, especially investing. Because what part of their success is down to being on the far right tail of the distribution by chance”. I was therefore delighted when I found out that chapter 16 of The Most Important Thing is entitled Appreciating the Role of Luck. And for Marks, the proof is in the pudding; Oaktree’s investments in distressed debt in Q4 of 2008 yielded 50-100% in the subsequent 18 months. This is the exact type of trade mentioned above. Marks has talked the talk and walked the walk – a rare thing in the world of finance. I cannot recommend his work enough.

    1. More astute readers will recognise that this doesn’t stop at second order moments. Even higher order moments are important but the intuition becomes difficult (and superfluous) beyond the second. ↩︎
    2. I point readers towards semi-variance and the Sortino ratio to measure the risk of loss. ↩︎
    3. You may also want to think about the intercept of the capital market line with the return axis – the expected return when we don’t take on any risk. This can also change throughout the cycle. This is important but surplus to requirements in the context of this post. ↩︎
  • The Odd Hobby of Wisden Collecting

    The Odd Hobby of Wisden Collecting

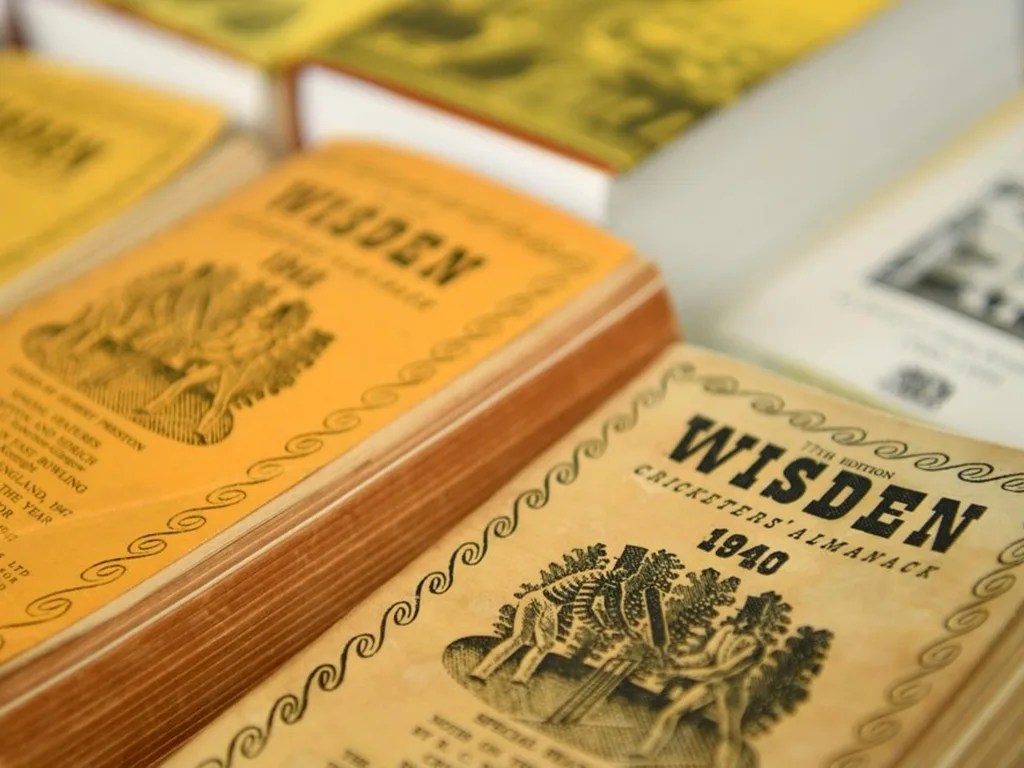
    If you’ve ever visited the home of a cricket enthusiast, a so-called badger in cricket-lingo, you may have noticed a set of yellow books on their bookshelves. These books are short and thick with faded spines. But despite their unassuming nature, these collections often form the crown jewels of one’s library. Those in the know will instantly recognise that I refer to Wisden Cricketers’ Almanacks.

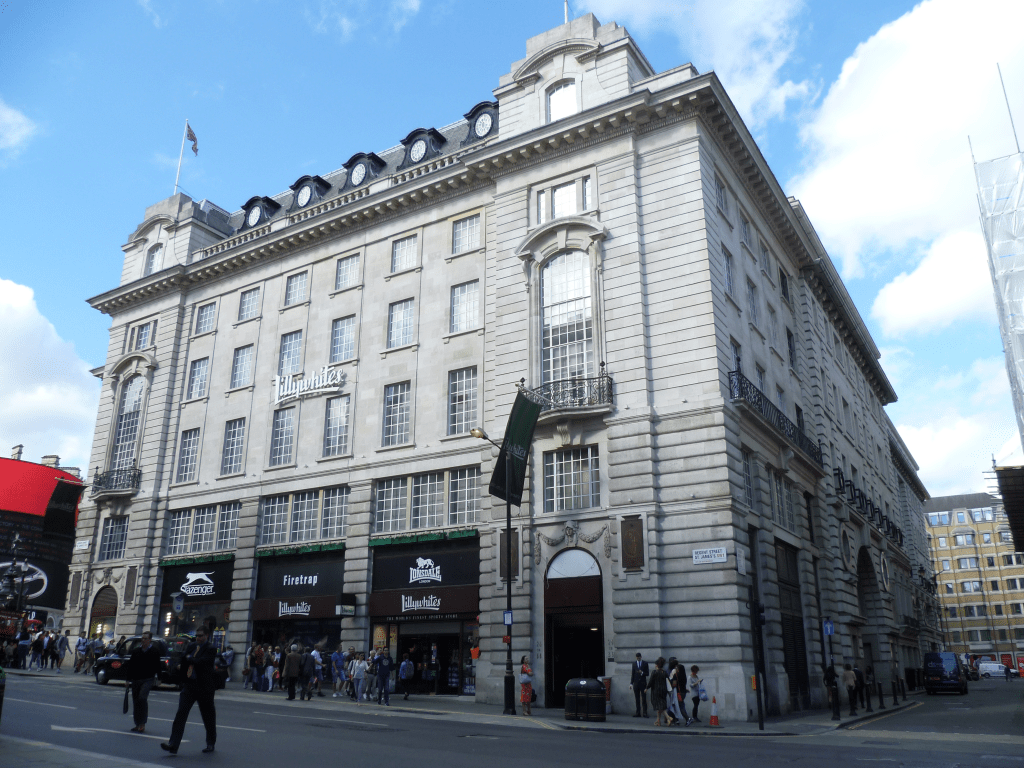
    Wisden Cricketers’ Almanacks, more commonly referred to as Wisdens, are an annual cricketing publication. The first Wisden was published in 1864 and has continued uninterrupted ever since. Founded by English cricketer John Wisden, a 5ft 4ins fast bowler nicknamed The Little Wonder, the publication started as a competition to Fred Lillywhite’s The Guide to Cricketers. You may recognise the name Lillywhite; I first read it in a P. G. Wodehouse where Bertie Wooster spoke of having purchased a single all-purpose golf club from the Lillywhite’s sporting goods store. Such a store still exists today in Piccadilly but you can probably tell from the image below that it no longer reflects its rich heritage.

    Lillywhite’s in Piccadilly, London

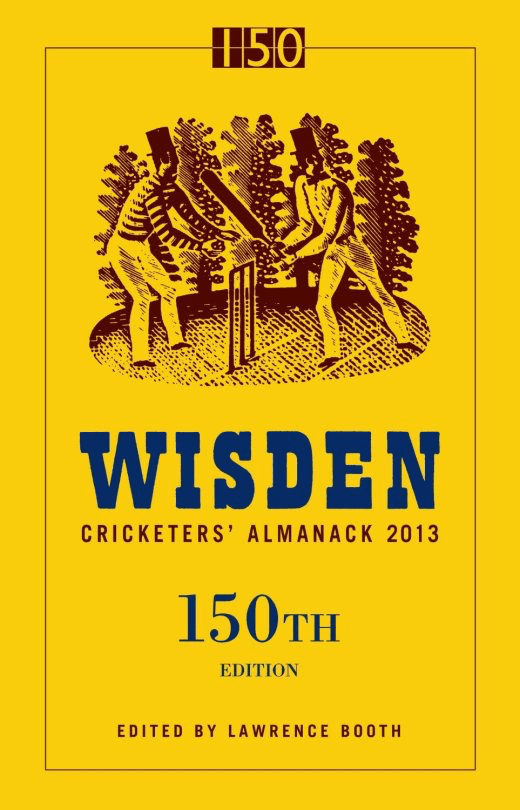
    The cover of a Wisden remains its most iconic feature. Since the 75th edition in 1938, the publication has carried a bright yellow cover displaying the famous woodcut of two cricketers by Eric Ravilious. This woodcut was abandoned in 2003 in favour of photograph of a famous cricketer, that year a picture of Michael Vaughan. The woodcut returned, however, in 2013 to mark the 150th anniversary of the almanack.

    The contents of a Wisden range from records to commentary on games. Editions even occasionally contain dialogue on new laws of the game. And by no means does Wisden discriminate against any form of the sport; within the same yellow cover one will find scores of international tests held at Lord’s and English schoolboy games held on dodgy wickets.

    One might expect Wisden to have suffered a similar fate to phone books; ESPN Cricinfo is a much more accessible and effective source for cricketing statistics. Yet that hasn’t been the case. Wisden’s are today an unbelievably popular collectors item. The desire to maintain a full collection guarantee sales every April when the preceding years edition is published; each new edition of Wisden still sells around 35,000 copies. The earliest copies of Wisden, which were originally sold at a shilling per piece, now fetch thousands of pounds at auction. A full set is today worth over £100,000.

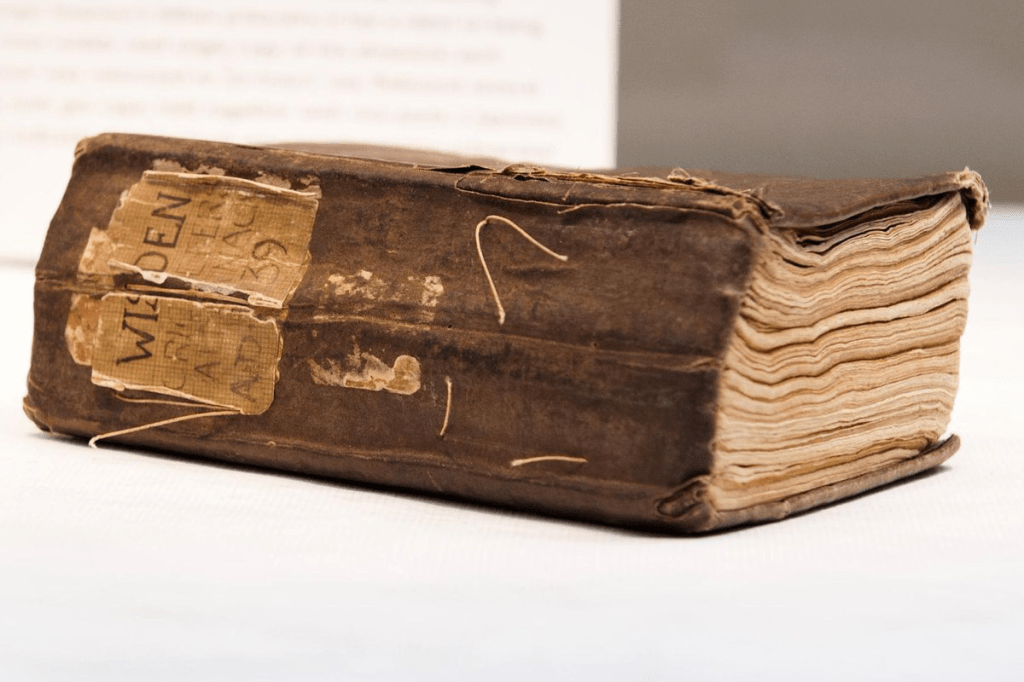
    E. W. Swanton’s 1939 Wisden

    The most famous single copy of Wisden is a 1939 edition which belonged to distinguished cricket writer, E. W. Swanton. Swanton had it with him when he was taken prisoner by the Japanese when wounded in the Battle of Singapore. The copy proved so popular with the other prisoners of war that it had to be reserved in advance like a library book, and could be borrowed for no more than 12 hours. It was stamped “not subversive” by the guards and was so heavily handled that two prisoners rebound it using rice paste as glue. Today the book resides in the museum at Lord’s. Swanton later went on to describe his experience of playing cricket with makeshift equipment and under conditions of extreme privation and the constant threat of brutality in an article, Cricket under the Japs, for the 1946 edition of Wisden.

    It is hard to think of something that embodies the spirit of English cricket more than Wisdens and the pursuit of collecting them. Not only does it capture the history of cricket, but given the enduring nature of the publication and the global reach of the game, Wisdens capture much more. The story of Swanton’s 1939 copy exemplifies the visceral nature of Wisden collecting, a hobby that many will find difficult to understand. I hope this post inspires you to try and find and flick through a Wisden at some point – an interesting scorecard or witty piece of commentary is sure to brighten any cricket enthusiasts day…

  • Why did Fama stop at Financial Markets?

    Why did Fama stop at Financial Markets?

    My undergraduate dissertation had the ever catchy title An Investigation into the Effects of Passive Investing on Equity Market Efficiency. I won’t bore you with the results; I certainly won’t bore you with the methods by which I went about getting them.1 Instead, I thought it may be interesting to think about the applications of efficient market theory to non-financial markets.

    I had the idea of writing this post when scrolling through Bridge of Highs, an anonymous online submissions page for Johnians where they can share thoughts on a variety of topics. This may range from complaints about rent prices to discussions about classist ent themes (as was the case for an après-ski themed ent). A few recent posts complained about how busy the John’s bar has become on a Friday with a sudden influx of guests from other colleges – a phenomenon which has inspired a campaign coined Jexit. A rather witty comment by a friend wrote “Bar is good on Friday? I’m bringing all of my friends next week”. The comment, deservingly in my opinion, received 20 likes. Although I can appreciate how funny this comment is, my first thought was that this was a brilliant case of how markets deal with information. Unfortunately I didn’t attend the subsequent Friday bar to see how the information was incorporated into market outcomes but I suspect it improved efficiency.

    Fama, who won the 2013 Nobel prize in Economics

    If all this jargon about markets, information and efficiency is confusing, let me explain. In 1970, Eugene Fama, who many consider to be the world’s most influential finance professor, published a paper on efficient capital markets. The paper defines an efficient market as one in which “prices at any time fully reflect all available information”. Consider the stock price of Apple for example. If some information becomes available that the new iPhone is incredibly popular, market participants (in this context, equities traders) will buy the Apple stock. The price of the stock will thereby rise and then new information about the new iPhone’s popularity is now incorporated into the price. The price, therefore, captures all sorts of information about Apple and its stock. Eugene Fama essentially formalised this idea and provided ways of testing for it in capital markets like stock markets, bond markets and derivatives markets. But Fama’s idea doesn’t have to be restricted to such contexts, it can even be applied to the market for cheap booze at St John’s College bar on a Friday night as I alluded to in my exposition.

    Fama focussed on prices being a signal for information. In asset markets, changes in demand and supply are almost instantaneously incorporated into prices. This is especially the case for liquid assets with lots of trading volumes, like the case of the Apple stock. However, this isn’t the case for many market. For example, the price of a double G&T at John’s bar has been £4.50 for as long as I can remember – this won’t change on a certain day just because the bar is especially busy. Therefore, focussing on prices in such a market is inappropriate; we must find another measure of efficiency.

    I can think of lots of information signals in markets beyond prices: boards displaying the number of available parking spots at a car park, signs estimating the queuing time for a ride at Disney Land and even the Google feature that states how busy a certain venue is at a certain time. In the absence of (flexible) prices, the market has devised its own way of passing information to buyers. But how do we build in the idea of efficiency?

    Well classical market efficiency is about how prices adjust to reflect available information. Maybe in such contexts with fixed prices, we may consider how supply and demand adjust (in the absence of a price adjustments) to incorporate new information. Will Google displaying that a certain coffee shop is very busy at a certain time deter customers from going when it’s busy? It probably will, and those who are more averse to long queues and busy spaces are more likely to be deterred than others, thereby improving welfare in the market.

    Rosslyn, London Wall, a very popular coffeeshop in the City

    We live in an increasingly information driven world and there has been a recent drive for information to be disseminated to and utilised by the masses. Think about the rising popularity if Polymarket, a cryptocurrency based prediction market that values the incorporation of market participants beliefs into placing odds on events. More widely, think about the current actions of Elon Musk with DOGE, arguing for more transparency over government spending. A recent project by my favourite political magazine, the Spectator Project against Frivolous Funding (or SPAFF) attempts to do the same thing for Britain. Efficient market theory probably remains the most developed framework for thinking about information and I suspect its applications extend beyond just the financial markets.

    1. For those interested, my dissertation is available here. ↩︎